Dispute management for issuers, acquirers and processors
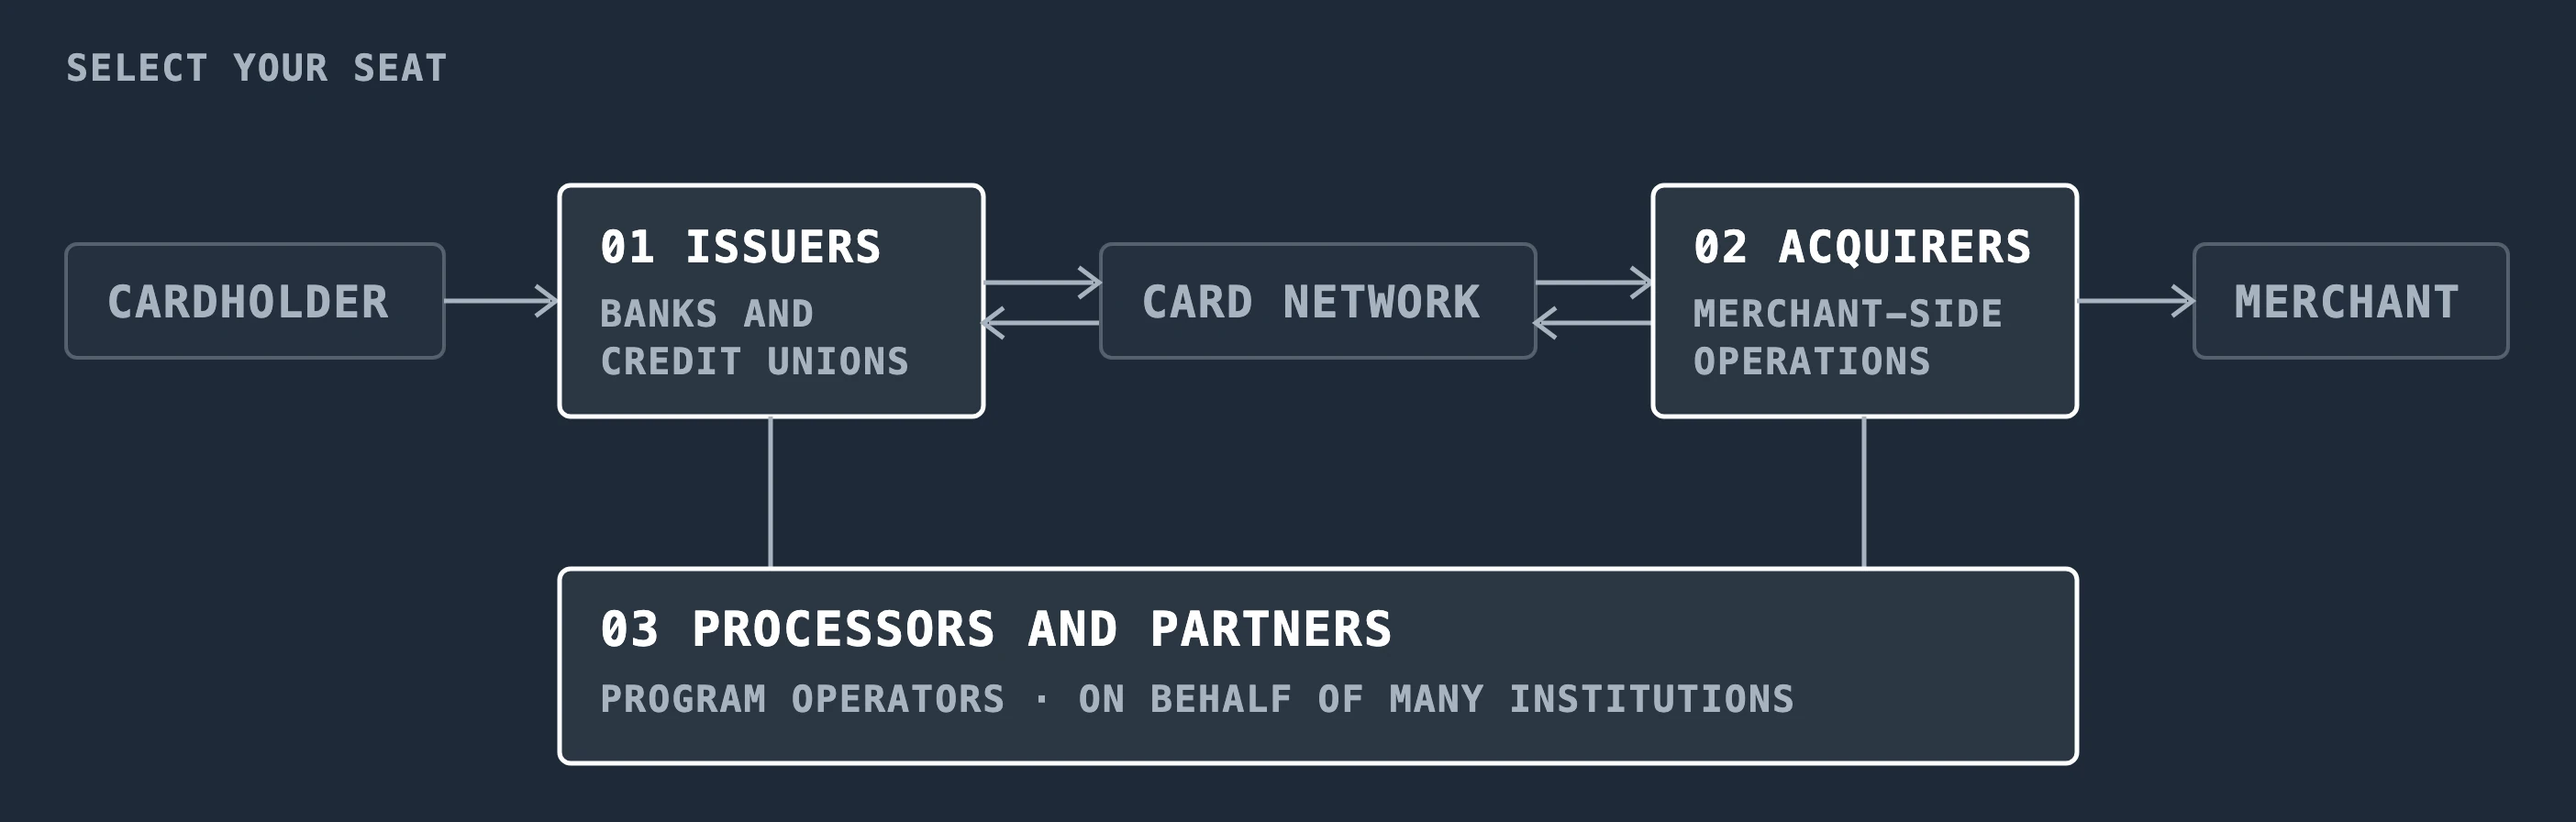
One platform, seen from the seat you work from. The dispute logic is the same for issuers, acquirers and processors; what changes is the job, the clocks and who is on the other side of the case. Card and non-card, fraud and non-fraud, in North America, Europe, South America and New Zealand.
Cardholder disputes, end to end.
Start the dispute from digital banking, the contact centre or the branch. Report fraud to the network databases from the same record. Settle early through Ethoca and Verifi when that costs less than filing. Run chargeback cycles and representment against Visa VROL and Mastercom, and file the case with the record already in order. Reg E and Reg Z timers, provisional credit and cardholder letters run from the case.
Covers: debit, credit and prepaid cards; ACH; wire; ATM; bill pay; cheques; Zelle.
Runs as: an enterprise deployment, configured to match your operation.

Through your processor today, or direct once the integrations are scoped.
Credit unions run AdjustmentHub today through their processor. If you run your own dispute operation, the fit depends on your core and card-processing integrations, which Lean builds during the implementation. Talk to a dispute specialist about your volume and integrations first.

Inbound chargebacks at volume.
Second presentments, evidence assembly, fee handling and merchant communication run on the same engine and rails as the issuer side. Acquirer workflows are native to it. Nearly every module comes in issuer, acquirer and combined configurations.
72% less time per dispute, and dispute-operations staffing from seven to three, at a global acquirer running AdjustmentHub.1

Many institutions, one configured platform.
Operate dispute programs on behalf of many institutions with per-institution policy held in configuration, a multi-tenant environment, and Visa VROL and Mastercom connectivity built in. Multi-institution configurations are in production today, at processor scale.
Delivered through ACI Worldwide as Automated Dispute Manager (ADM) for institutions on ACI issuing and acquiring platforms. See Partners.

Frequently asked questions
Does AdjustmentHub support both issuers and acquirers?
Yes. Nearly all modules are available in three configurations: issuer, acquirer, and enterprise (combined issuer and acquirer). A small number of modules apply to one side only because the scenario is specific to it.
Can a processor run AdjustmentHub for many institutions?
Yes. AdjustmentHub is multi-tenant, with per-institution policy held in configuration, and multi-institution deployments are in production today.
Is AdjustmentHub limited to card disputes?
No. It handles ACH, wire, ATM, bill pay, cheque and Zelle disputes as well as debit, credit and prepaid card disputes. Local rules for non-card disputes may need additional configuration.
Does AdjustmentHub work for a credit union?
Credit unions use AdjustmentHub today through their processor. A credit union running its own dispute operation should confirm the core and card-processing integrations needed, since the implementation builds them.
See it from the seat you work from.
30 minutes, your numbers, no deck.